Skip to content
Public Record
Laguna Vista · Money & SpendingACTIVE — AWAITING SUPPORTING RECORDS

General Fund Reconciliation Questions

Reported FY2026 figures contain different balances and net-change figures. The question is not where money ‘went.’ The question is what accounting entries, adjustments, reclassifications, or reconciliations explain the differences.

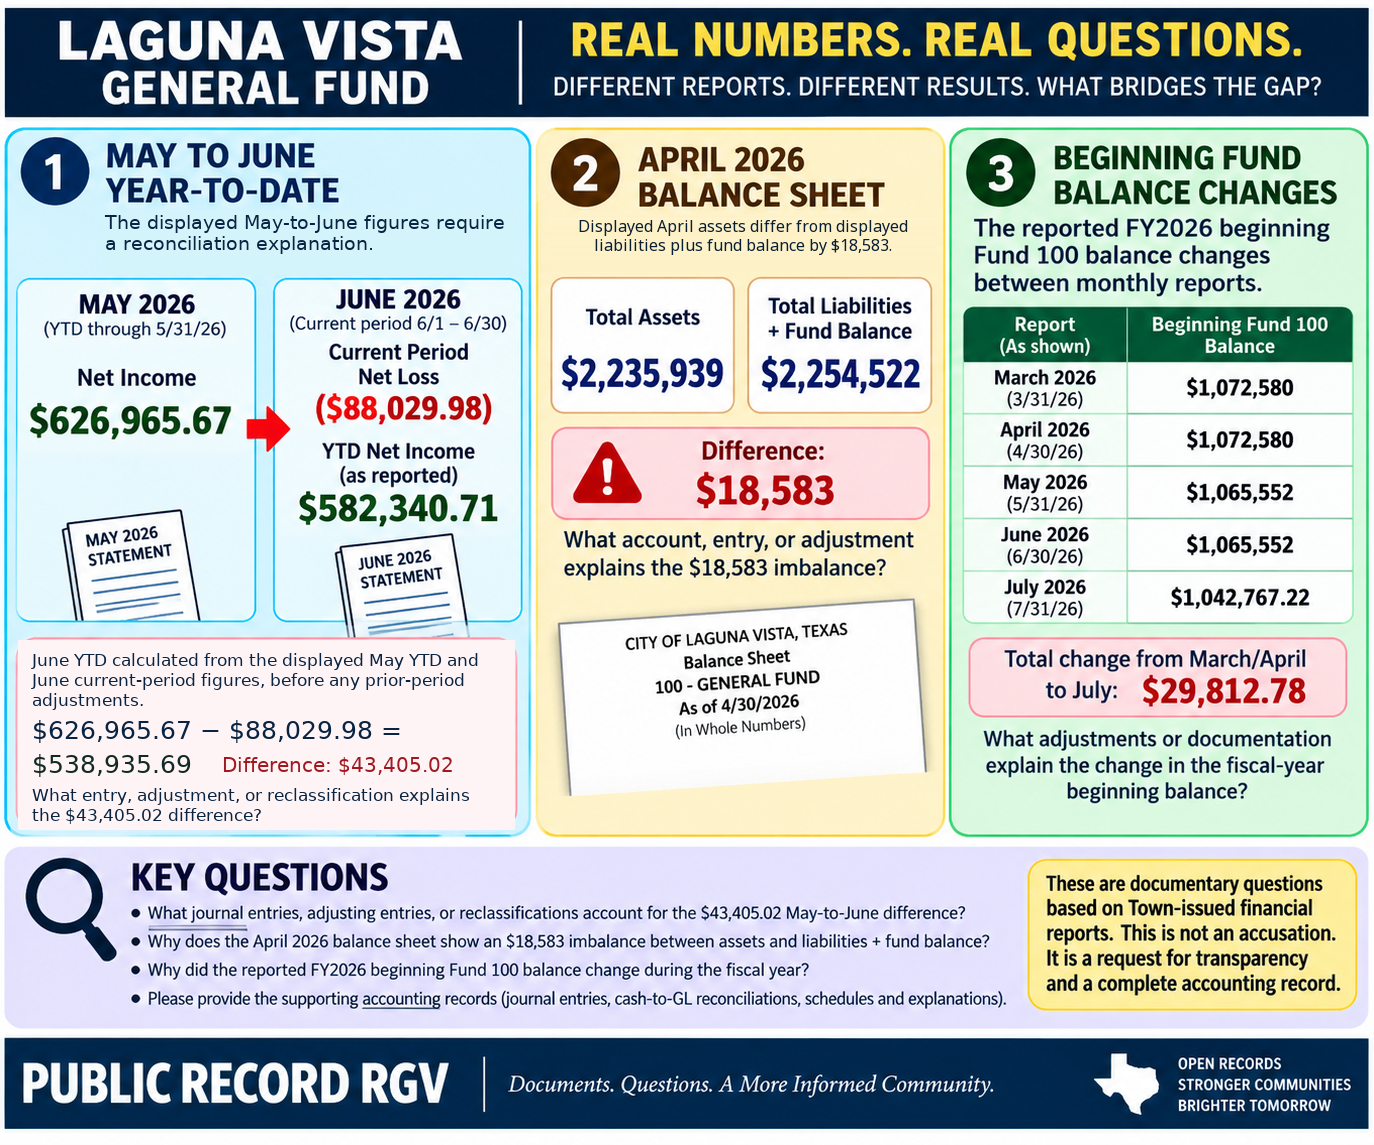
Analysis infographic comparing FY2026 General Fund figures: May-to-June calculated net income, displayed April assets versus liabilities plus fund balance, and reported beginning balances. Report icons are illustrations, not document excerpts.
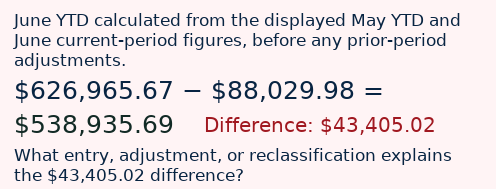
Calculation detail: June YTD calculated from the displayed May YTD and June current-period figures, before any prior-period adjustments. $626,965.67 minus $88,029.98 equals $538,935.69. Difference: $43,405.02.
Analysis of reported figures — supporting reconciliation not yet established.This infographic summarizes unresolved reconciliation questions based on reported FY2026 figures. It is a visual summary, not a finding of wrongdoing.The displayed May-to-June figures require a reconciliation explanation.Each illustrated report icon: Illustration — not a document excerpt.June YTD calculated from the displayed May YTD and June current-period figures, before any prior-period adjustments.This comparison assumes matching report scope and no intervening revisions.

Source trail and caveats

Evidence layer

The relevant source files are not attached to this page. Each unverified citation field below is marked “Source citation pending.” No download link is supplied until the source passes editorial and redaction review.

  • FY2026 monthly General Fund balance sheetsPublication pending
  • FY2026 Statements of Revenues and ExpendituresPublication pending
  • ORR-2026-101 request and production correspondencePublication pending

Source verification remains incomplete. The recordings confirm only what the page displayed; they do not independently verify the financial inputs, report titles, reporting dates, print/version dates, page numbers, or row labels.

Reported FY2026 figures require reconciliation. The accounting records needed to explain the differences remain outstanding or have not yet been identified in the partial ORR production. This page does not characterize any difference as missing money, fraud, misconduct, theft, or intentional manipulation.

Evidence review

What the records show

Reported FY2026 beginning balance changed

Reported FY2026 Beginning Fund Balance amounts
Reported itemAmount
March / April 2026
Report title:
Source citation pending.
Reporting date:
Source citation pending.
Print/version date:
Source citation pending.
Page number:
Source citation pending.
Row label:
Source citation pending.
$1,072,580
May / June 2026
Report title:
Source citation pending.
Reporting date:
Source citation pending.
Print/version date:
Source citation pending.
Page number:
Source citation pending.
Row label:
Source citation pending.
$1,065,552
July 2026
Report title:
Source citation pending.
Reporting date:
Source citation pending.
Print/version date:
Source citation pending.
Page number:
Source citation pending.
Row label:
Source citation pending.
$1,042,767.22

March–June beginning balances are displayed in whole dollars; July includes cents. The $29,812.78 comparison uses those displayed values.

Total change $29,812.78

Precision note: These are reported “Beginning Fund Balance” amounts and must not be characterized as prior-month ending balances.

Open question

What accounting entries, prior-period adjustments, restatements, or reclassifications explain why the reported FY2026 beginning Fund 100 balance changed during the fiscal year?

May same-period figures do not match

May 2026 same-period General Fund figures
Reported itemAmount
May 31 General Fund balance sheet — Net Change
Report title:
Source citation pending.
Reporting date:
Source citation pending.
Print/version date:
Source citation pending.
Page number:
Source citation pending.
Row label:
Source citation pending.
$641,372
May Statement of Revenues and Expenditures — Net Income
Report title:
Source citation pending.
Reporting date:
Source citation pending.
Print/version date:
Source citation pending.
Page number:
Source citation pending.
Row label:
Source citation pending.
$626,965.67
DifferenceCalculated from the displayed inputs; not a source-report row.$14,406.33

Open question

What entry, adjustment, reclassification, or other accounting item reconciles the $14,406.33 difference between the displayed figures for the same reporting period?

June same-period figures differ

June 2026 same-period General Fund figures
Reported itemAmount
June balance sheet — Net Change
Report title:
Source citation pending.
Reporting date:
Source citation pending.
Print/version date:
Source citation pending.
Page number:
Source citation pending.
Row label:
Source citation pending.
$582,390.71
Revenue-and-expenditure statement — YTD Net Income
Report title:
Source citation pending.
Reporting date:
Source citation pending.
Print/version date:
Source citation pending.
Page number:
Source citation pending.
Row label:
Source citation pending.
$582,340.71
DifferenceCalculated from the displayed inputs; not a source-report row.$50.00

The amount is small but still requires reconciliation before the figures are assumed equivalent.

Open question

What accounting entry or report correction explains the $50.00 difference?

May-to-June rollforward needs explanation

May-to-June net-income rollforward
Reported itemAmount
May YTD net income
Report title:
Source citation pending.
Reporting date:
Source citation pending.
Print/version date:
Source citation pending.
Page number:
Source citation pending.
Row label:
Source citation pending.
$626,965.67
June current-period activity
Report title:
Source citation pending.
Reporting date:
Source citation pending.
Print/version date:
Source citation pending.
Page number:
Source citation pending.
Row label:
Source citation pending.
($88,029.98)
June YTD calculated from the displayed May YTD and June current-period figures, before any prior-period adjustments.Calculated from the displayed inputs; not a source-report row.$538,935.69
June reported YTD net income
Report title:
Source citation pending.
Reporting date:
Source citation pending.
Print/version date:
Source citation pending.
Page number:
Source citation pending.
Row label:
Source citation pending.
$582,340.71
Difference requiring reconciliationCalculated from the displayed inputs; not a source-report row.$43,405.02

This comparison assumes matching report scope and no intervening revisions.

An adjustment, reclassification, backdated transaction, correction, or another accounting entry may explain this. It is not characterized here as missing money.

Open question

What adjustment, reclassification, backdated transaction, correction, or other accounting entry explains the $43,405.02 difference?

Displayed April assets differ from displayed liabilities plus fund balance by $18,583.

April 2026 General Fund balance-sheet totals
Reported itemAmount
Total Assets
Report title:
Source citation pending.
Reporting date:
Source citation pending.
Print/version date:
Source citation pending.
Page number:
Source citation pending.
Row label:
Source citation pending.
$2,235,939
Liabilities + Fund Balance
Report title:
Source citation pending.
Reporting date:
Source citation pending.
Print/version date:
Source citation pending.
Page number:
Source citation pending.
Row label:
Source citation pending.
$2,254,522
DifferenceCalculated from the displayed inputs; not a source-report row.$18,583

No “ending cash” amount is calculated from this difference. Cash, assets, liabilities, and fund balance are different accounting categories.

Open question

What account, correction, entry, or report revision explains the displayed $18,583 difference?

Important accounting clarification

Modified accrual does not eliminate reconciliation

Laguna Vista’s governmental-fund reports use modified-accrual accounting. That accounting method can affect when revenues and expenditures are recognized, but saying ‘modified accrual’ does not itself reconcile two different figures. If timing, an adjustment, or a reclassification explains a difference, the supporting accounting record should identify it.

Restricted reserves and cash are not interchangeable concepts. A restricted fund balance describes how resources are classified; it should not automatically be added to another fund-balance figure and labeled ‘cash on hand.’

Connected records status

ORR-2026-101 — records that could answer these questions

OUTSTANDING / PARTIAL PRODUCTION
  1. Submitted

  2. Town’s anticipated production

  3. Partial production — 16 files

  4. City Secretary stated she was still waiting for Finance to provide remaining material

  5. 89 calendar days since submission

Evidence/status snapshot last reviewed September 21, 2026

Elapsed figures are measured through September 21, 2026. This snapshot does not establish whether later responses or records were received.

Since anticipated July 15 date
68 days
Since partial August 3 production
49 days
Since August 5 statement
47 days

Precision note: Texas TPIA uses a “promptly” standard rather than a universal fixed 90-day production deadline. This page does not make an adjudicated legal-violation claim.

Requested records relevant to reconciliation

  • AWAITINGTrial balance
  • AWAITINGGeneral-ledger detail
  • AWAITINGJournal entries
  • AWAITINGAdjusting and reclassification entries
  • AWAITINGCash-to-general-ledger reconciliation
  • AWAITINGBank reconciliations
  • AWAITINGBeginning-to-ending fund-balance rollforward
  • AWAITINGFund-balance classification schedules
  • AWAITINGInterfund transfer schedules
  • AWAITINGSupporting calculations for the $883,189 90-day reserve
  • AWAITINGReserve worksheets and supporting authorization
  • AWAITINGRelevant financial-management / fund-balance / reserve policies

These records were requested because they provide the accounting bridge between reported balances. They have not yet been identified in the partial production reviewed for this project.

Read the original ORR-2026-101 record and production timeline →View ORR-2026-101 in the Open Records Tracker →ORR-2026-155 — compare two Fund 100 reports for September 30, 2025 →

Source verification is in progress. Reconciliation remains unresolved; the reporting difference does not establish missing money or wrongdoing. The FY2026 monthly comparisons above are a separate evidence set from the $153,668 difference between two reports for September 30, 2025; their citations and conclusions are not interchangeable.

Open question

What accounting records reconcile the changing FY2026 beginning Fund 100 balances and the differing reported net-change/net-income figures displayed on this page?

Secondary question: When will the remaining reconciliation and journal-entry records requested under ORR-2026-101 be produced?

Council question

Open to read full text

Mayor and Council,

Regardless of where this public comment falls tonight, I ask that it be treated as a request for Council oversight of the Town’s financial records, budget decisions, and use of taxpayer money.

Before the September 8 budget hearing, I asked for a properly noticed special meeting or agenda item so budget and financial questions could be resolved before final action.

That did not occur.

My concern is not that Council must personally do the bookkeeping. My concern is that Council is being asked to make final decisions about residents’ tax dollars while important supporting Finance records remain unavailable.

ORR-2026-101 was submitted June 24 and remains only partially produced. The missing records include the trial balance, general-ledger detail, cash reconciliations, fund-balance rollforward, journal entries, and reserve-support records. Those are the records needed to explain differences appearing in the Town’s own reports.

I am not alleging that money is missing or that anyone acted improperly. I am asking what Council will do when the accounting records needed to answer legitimate questions about public funds have not been produced.

The Charter provides for an Audit Committee. Please identify the current Audit Committee. If no Committee has been designated, will a Council member propose placing its appointment on the next agenda?

the September 8 minutes state a maintenance-and-operations tax rate of $0.415964 and an interest-and-sinking rate of $0.013160. Before final action on any tax-rate ordinance, will staff or the Town Attorney state on the record whether those remain the Town’s official allocations?

If they do not, please state the current M&O and I&S rates, when they changed, and identify the Council action or correcting record that supports the change.

Please verify the library budget balances before the vote as well.

Finally, I also request that Council place on that agenda a written status report on ORR-2026-101: what Finance records remain outstanding, who is responsible for producing them, and the date they will be available. The Audit Committee, once identified or appointed, should receive the documented reconciliation questions and recommend what records or independent professional review are needed.

Council is not being asked to assume wrongdoing. Council is being asked to ensure that the Town can show its work before and after it spends residents’ tax dollars. Thank you.
Other referenced financial inputs

$883,189 90-day reserve — supporting calculation requested

Report title:
Source citation pending.
Reporting date:
Source citation pending.
Print/version date:
Source citation pending.
Page number:
Source citation pending.
Row label:
Source citation pending.

Council question: $0.415964 M&O and $0.013160 I&S rates

Report title:
September 8 minutes
Reporting date:
September 8, 2026
Print/version date:
Source citation pending.
Page number:
Source citation pending.
Row label:
Source citation pending.

Evidence limits

What this does — and does not — establish

SOURCE VERIFICATION INCOMPLETE
Reported FY2026 figures are displayed above; their underlying source documents remain subject to verification.
DOCUMENTED
Some same-period figures and reported beginning balances differ.
DOCUMENTED
ORR-2026-101 received a partial production and additional Finance records were still being awaited.
NOT ESTABLISHED
Missing money.
NOT ESTABLISHED
Fraud or intentional manipulation.
UNRESOLVED
The accounting entries or adjustments explaining the differences.
NEXT ACTION
Obtain the reconciliation records and update the page when the documentary bridge is produced.

Public Record RGV is not asking readers to assume what happened. We are asking for the accounting records that show what happened.